Absolutely. Here’s a polished blog post version you can use:
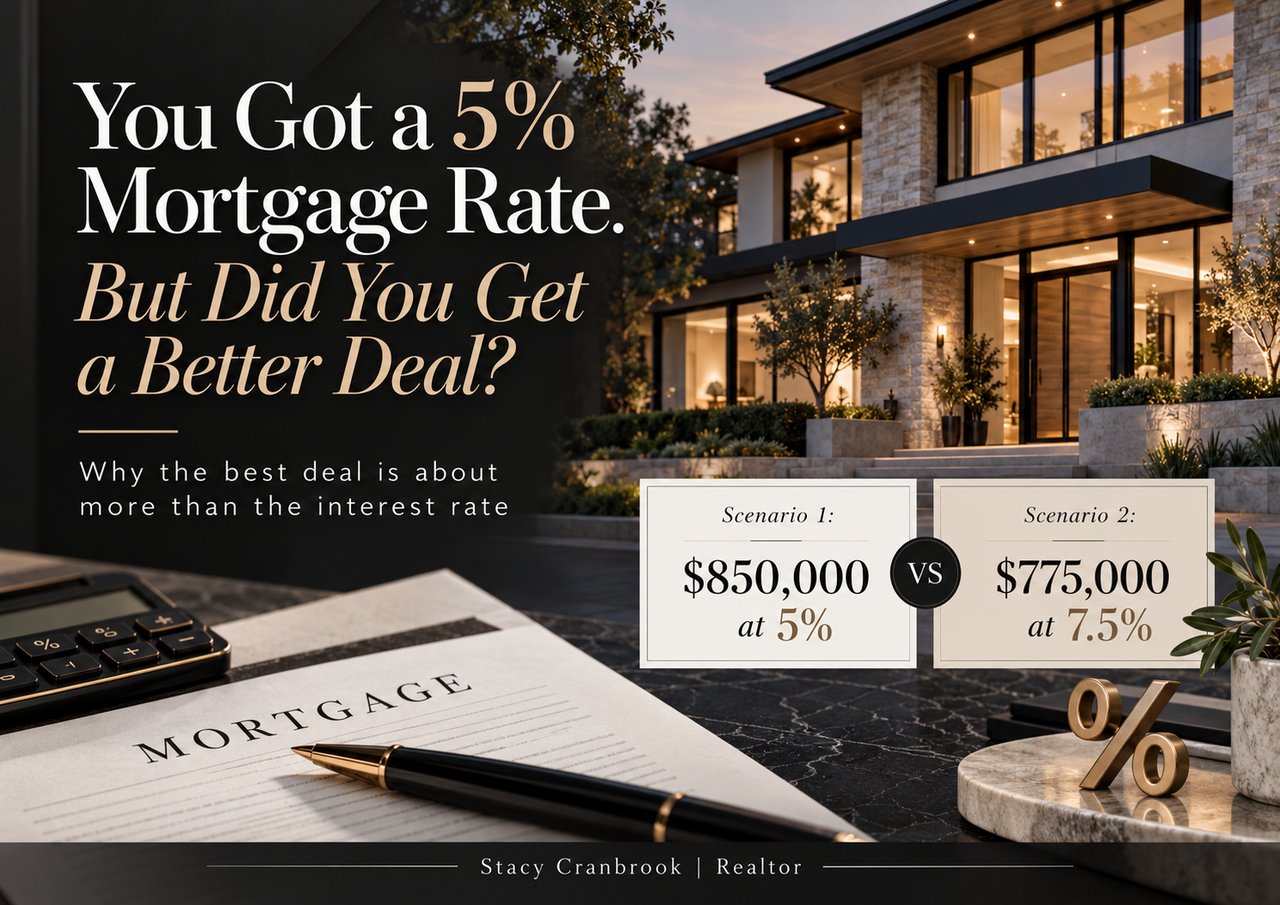
You Got a 5% Mortgage Rate. But Did You Get a Better Deal?
For the last few years, I’ve heard some version of this over and over again:
“I wish I had bought when rates were lower.”
And listen, I get it. A 5% interest rate sounds a whole lot sexier than 7.5%.
But if you’re only looking at the rate and not the full deal, you’re missing a huge part of the story.
Because a lower interest rate does not automatically mean you got the better deal.
Let’s look at a real example
Scenario 1: The “good old days”
- Home listed at $800,000
- Buyer has to offer $50,000 over asking
- Purchase price = $850,000
- 10% down
- 5% interest rate
Scenario 2: Today’s market
- Home purchased for $775,000
- 10% down
- 7.5% interest rate
At first glance, most people immediately assume the 5% rate is the better deal.
And from a monthly payment standpoint, it is.
- $850,000 purchase at 5% = about $4,107/month in principal and interest
- $775,000 purchase at 7.5% = about $4,877/month in principal and interest
That’s a difference of about $770 per month.
So yes, the buyer with the lower rate has the lower payment.
But that’s not the whole story.
What the numbers don’t tell you
A few years ago, buyers weren’t just getting a lower interest rate. They were also dealing with:
- multiple offers
- bidding wars
- waived inspections
- appraisal gap coverage
- fewer contingencies
- very little negotiating power
In other words, buyers often had to do whatever it took to win.
Today, even with higher rates, buyers may have something they didn’t have back then:
Leverage
And leverage matters.
Today’s buyers may be able to:
- negotiate the purchase price
- ask for seller-paid closing costs
- keep inspection contingencies in place
- negotiate repairs
- ask for an interest rate buydown
That’s a very different buying experience than paying $50,000 over asking and hoping for the best.
Here’s the part people forget
You can refinance an interest rate.
You cannot refinance what you paid for the house.
That doesn’t mean today’s higher-rate buyer automatically got the better deal. Not even close.
Refinancing is never guaranteed. Rates may come down, or they may not. And refinancing costs money.
But it does mean buyers should stop comparing today’s rates to yesterday’s market without looking at the entire picture.
Because the real question isn’t:
“Which rate is lower?”
The real question is:
“What was the total deal, and what did that buyer have to give up to get it?”
The best deal is about more than the rate
A lower rate can absolutely save you money every month. That part is real.
But so are these questions:
- Did you overpay?
- Did you waive protections?
- Did you lose negotiating power?
- Did you buy under pressure?
- Did you inherit issues you didn’t fully investigate?
- Did you miss the chance to negotiate terms that matter?
Sometimes the lower-rate buyer got a fantastic deal.
Sometimes they just paid a premium to get in.
Both things can be true.
What this means for buyers today
If you’re buying in today’s market, don’t assume you’re losing just because rates are higher.
And don’t assume someone who bought at 5% automatically made the better move.
The best time to buy a house is not always when rates are lowest.
It’s when:
- the numbers make sense
- the property makes sense
- the terms make sense
- and your life makes sense
That’s the real answer.
Final thought
My job is not to tell people it’s always a good time to buy.
My job is to help people recognize a good opportunity when it shows up.
Sometimes that opportunity comes with a lower rate.
Sometimes it comes with more negotiating power.
And sometimes the smartest move is simply understanding the full picture instead of getting distracted by one number.
If you’re trying to decide whether buying now makes sense, let’s talk through the numbers and the strategy. Because the interest rate is only part of the story.